

Free report: “5 Things $39.6M in B2B Programmatic Spend Taught Us.” Three years of managed spend and a billion tracked page loads, turned into five findings platforms won’t put in a pitch deck. Subscribe free to unlock it, plus every new issue of The B2B Stack.
Join 1,600+ B2B marketers, including readers at Dentsu, HubSpot, 6sense, Informa and DirecTV.
On the 28th of February 2026, Microsoft quietly switched off the DSP it had bought from AT&T four years earlier for around a billion dollars. The platform had previously been Xandr, and before that AppNexus — for more than a decade one of the most respected names in programmatic, the open web’s most credible non-Google challenger, the centre of gravity of the AT&T adtech ambition that valued it at $1.6 billion in 2018. By 2026 it was gone. Microsoft kept the supply side (Monetize) and the curation layer (Curate). The buy side it simply stopped supporting. When I entered Adtech in the late noughies, AppNexus was the poster child of innovation, it was everything which was great about adtech - category creating even - so on a personal level its demise left a gap.
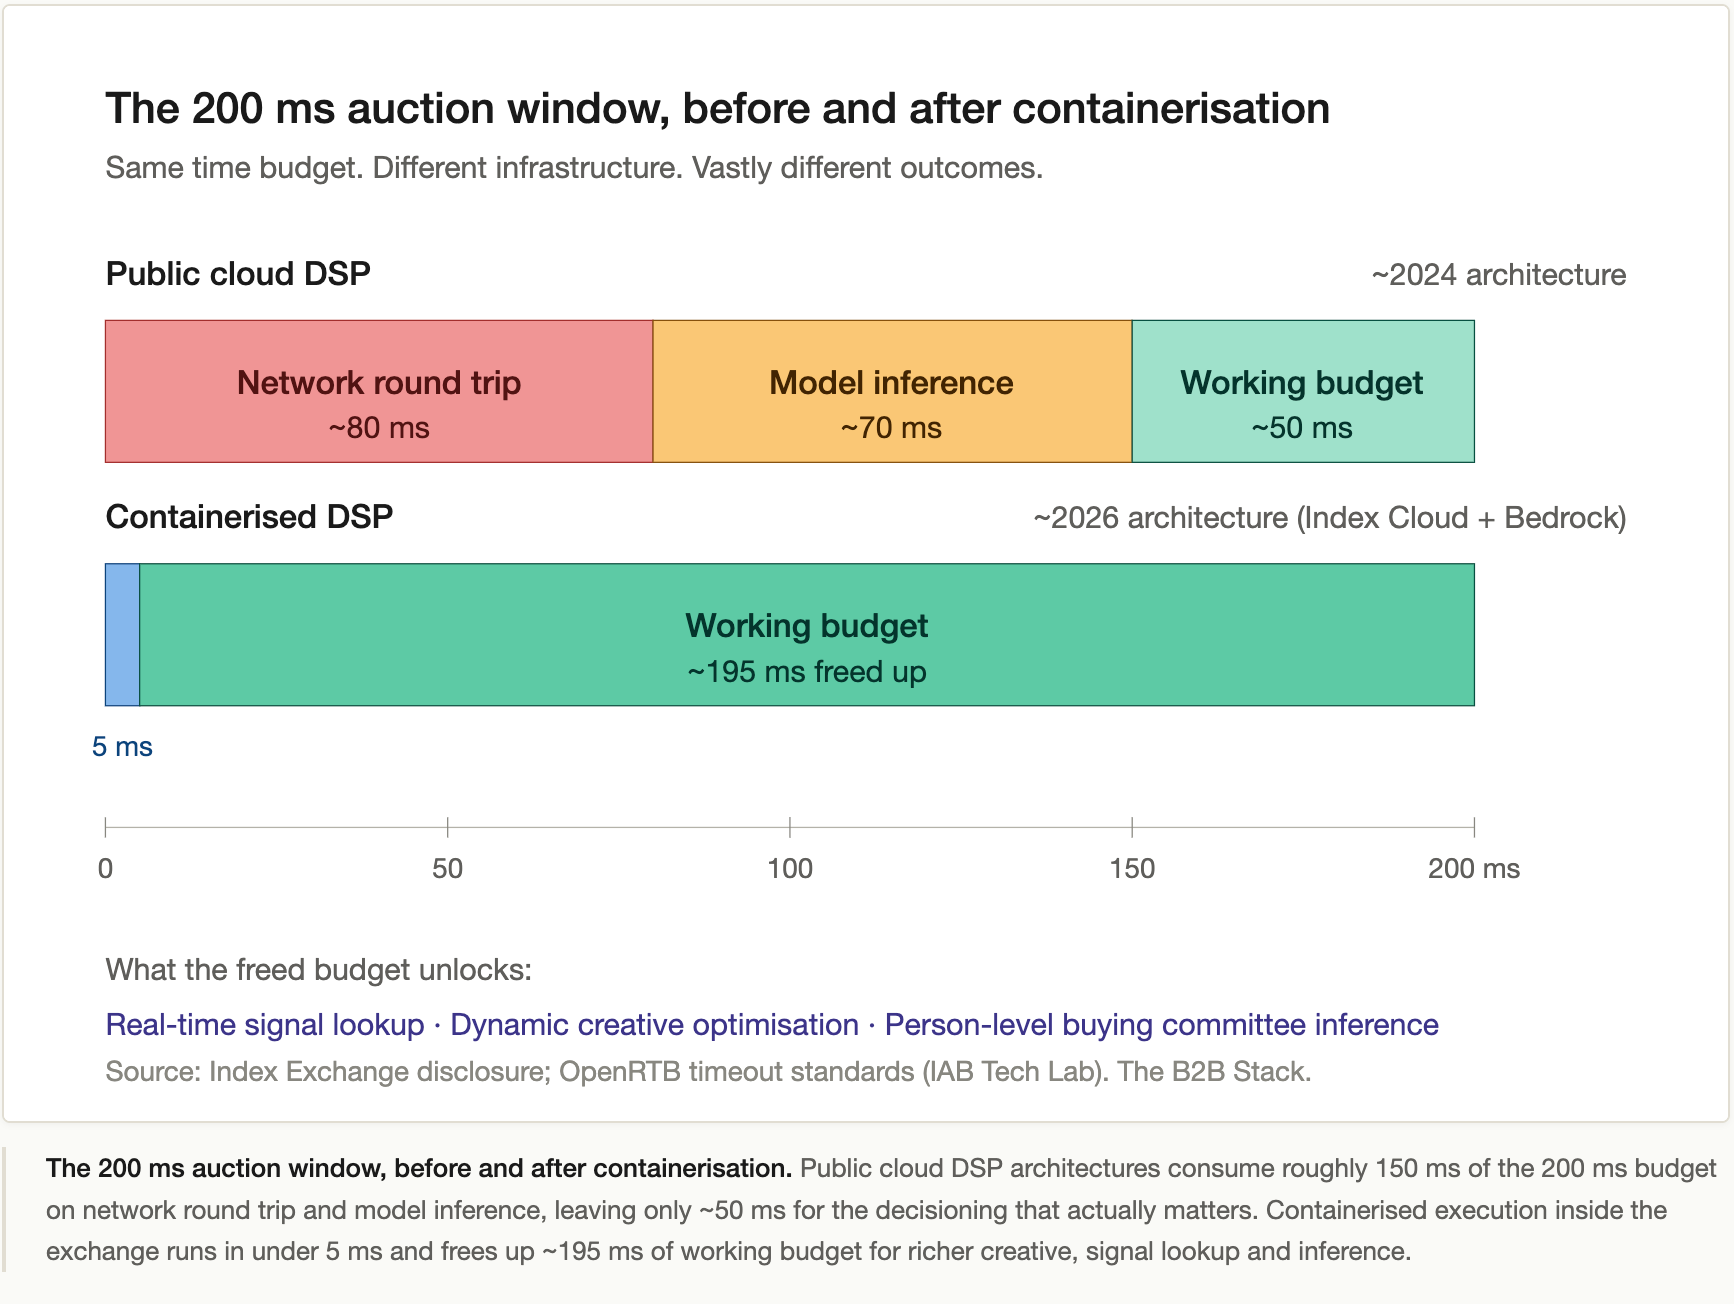
Two months later, on the 21st of April, Index Exchange, a leading sell side platform which has stayed true to its routes, and a two-year-old London-headquartered DSP called Bedrock Platform went live with the open web’s first containerised demand-side platform. Bedrock’s bidder, its full decisioning logic, was lifted out of public cloud infrastructure and dropped inside Index’s own data centres. The execution window for a bid decision collapsed to under five milliseconds. If you have spent any time at all around programmatic advertising, this is genuinely astonishingly fast and as we will come to shortly, it opens a lot of opportunities to re-use the time saving.
A few weeks after that, Andrew Casale, the President and CEO of Index Exchange, sat down with First Party Capital for an episode of The FPC Podcast and tied the threads together. The headline soundbite — “we are at the outset of a structural shift in programmatic” — is the sort of thing exchange CEOs say at trade shows. The substance underneath it is not. The two announcements ten weeks apart, taken together, mark the end of an orthodoxy that has shaped fifteen years of investment, M&A and product strategy across adtech. And they matter more, for structural reasons, to B2B programmatic than to almost any other corner of the open web.
If you have ever tried to find six chief financial officers across two hundred named accounts in a single quarter, you already understand why.
What you’ll learn in this article
Why for fifteen years every serious adtech business felt commercially obliged to be inside the DSP layer, and why that orthodoxy quietly died this spring
What “audience containerisation” actually means in plain English, and why moving the decisioning layer inside the exchange is structurally different from anything that came before
How the cost of looking at the bid stream became the dominant constraint on B2B targeting, and why mid-tier DSPs were always going to lose this fight on cost economics alone - this is why I always argued that B2B should not have its own bidding tech and should lean on the roadmaps of the giants.
Why live sports on connected TV exposed the queries-per-second problem in public, and why this matters more for needle-in-haystack B2B audiences than for the broad-reach buyers who have historically set platform agendas
How a five-millisecond decisioning window unlocks reactive, signal-driven creative — including person-level buying committee targeting that has been theoretical for a decade
What B2B marketing teams should actually do differently in the next twelve months as this shift compounds
Fifteen years of the wrong orthodoxy
For most of the last decade and a half, the unspoken rule of adtech strategy was simple: if you wanted to be a serious player on the open web, you needed exposure to the demand-side platform layer.
The reasoning, on a whiteboard, looked airtight. The DSP was where the bidding decision happened, where the data lived, where the optimisation models ran, where the margin sat. Own the DSP, or own a meaningful piece of one, and you owned the customer relationship, the bid economics, the integration roadmap, the strategic floor. Lose it and you were renting from someone else’s roadmap forever.
The agency holding groups built their version of this thesis through trading desks. WPP launched Xaxis in 2011, assembling it on the bones of GroupM’s earlier programmatic operations and the 2007 acquisition of 24/7 Real Media. Publicis had VivaKi Audience on Demand. IPG had Cadreon. Omnicom had Accuen. Havas built Affiperf. Dentsu had Amnet. By the mid-2010s most of the holdco trading desks had quietly decommissioned the in-house DSP layer and switched to running through external DSPs — Xaxis itself publicly mothballed its own DSP in 2013, explicitly because the technology had commoditised. They kept the audience layers, the supply relationships, the trading desks themselves. They gave up on operating the actual bidder.
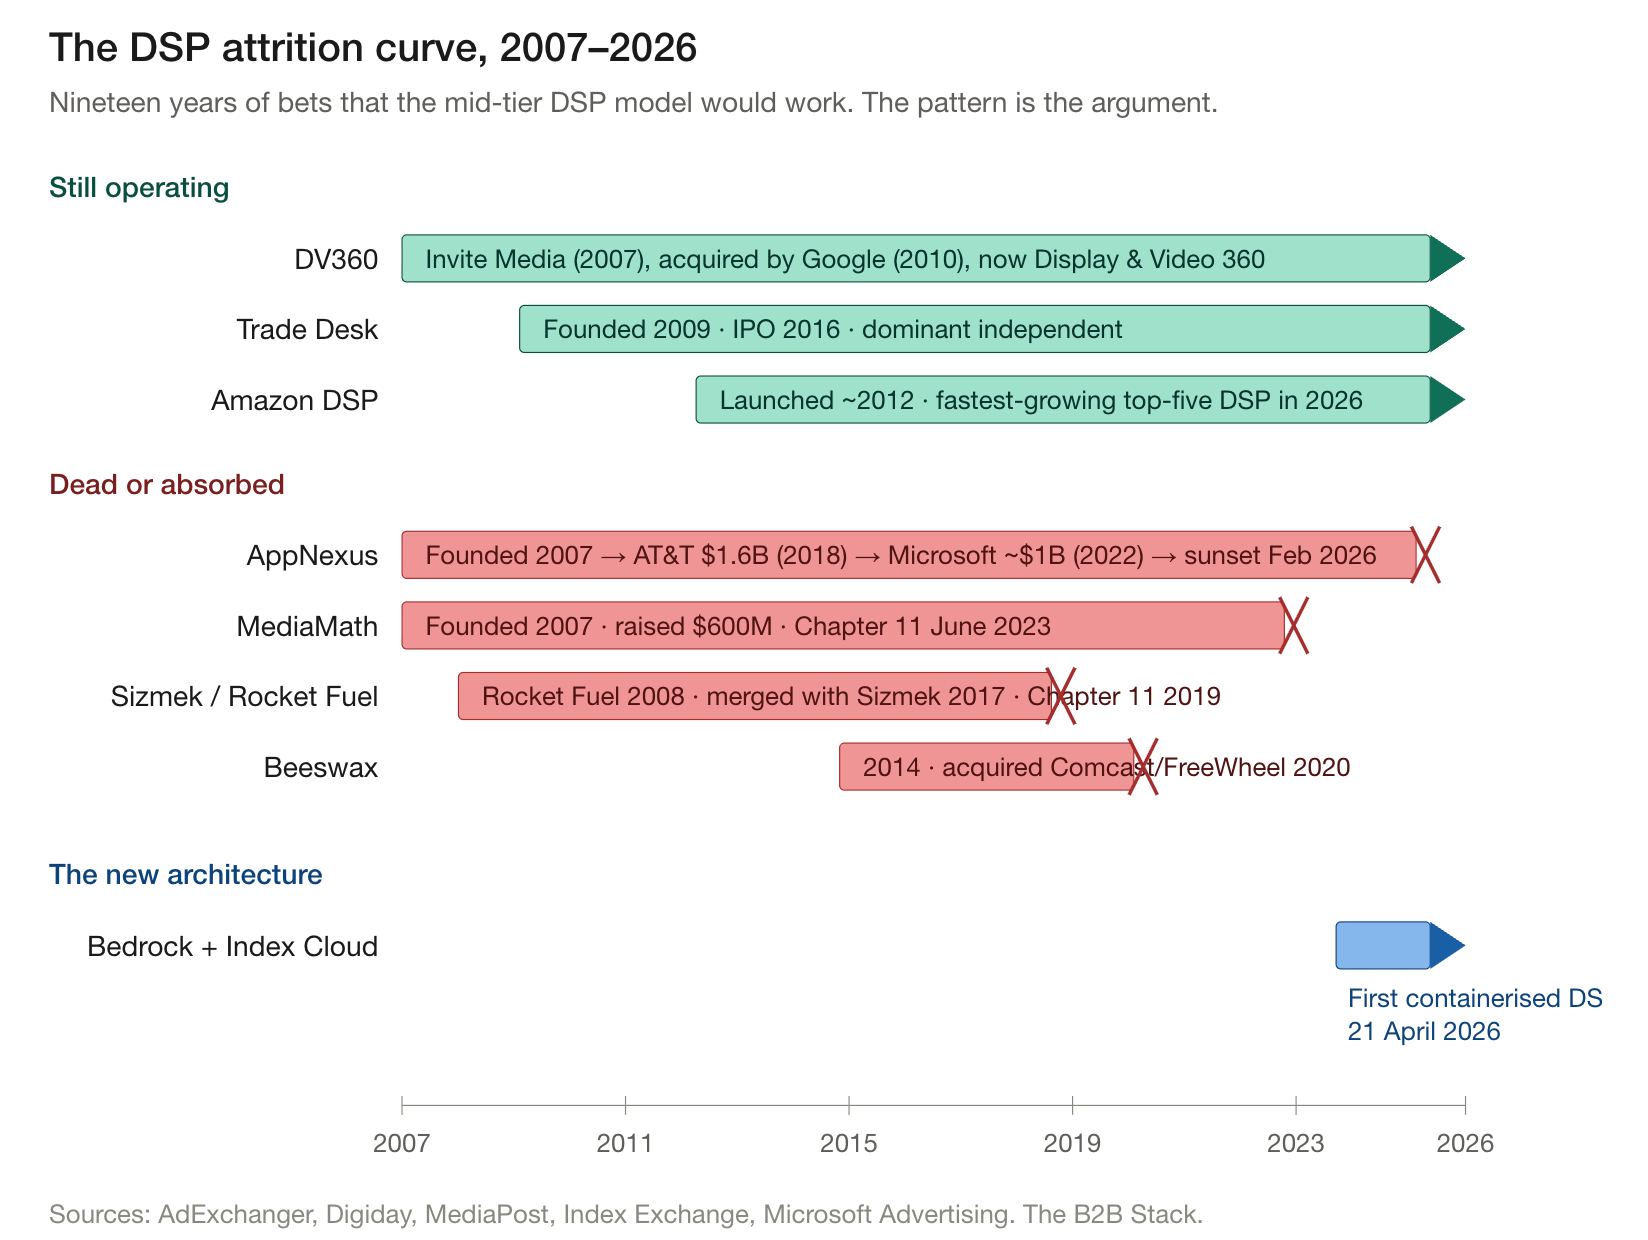
The pure-play DSPs followed a steeper version of the same arc. MediaMath raised about $600 million across its life, hit a peak valuation north of a billion, and filed for Chapter 11 in June 2023 owing somewhere between $100 million and $500 million to a creditor list that read like a roll call of the supply side. Sizmek absorbed Rocket Fuel in 2017 and went into Chapter 11 in 2019; Amazon picked up parts. Verizon paid $9 billion combined for AOL and Yahoo, merged them into Oath, wrote down $4.6 billion, and sold the lot to Apollo for $5 billion in 2021, half what it paid in. Beeswax was bought by Comcast and absorbed into FreeWheel. Basis (formerly Centro) remains a useful boutique alternative but isn’t competing at Tier-1 scale.
And then there was AppNexus. AT&T paid $1.6 billion for it in 2018, renamed it Xandr, sold it to Microsoft for around a billion in 2022, and watched Microsoft announce its closure in May 2025 before formally sunsetting the platform on the 28th of February this year. Microsoft, the second most valuable company in the world, with arguably the deepest cloud and AI moat in technology, could not make the mid-tier DSP economics work. The end state, in 2026, is that two general-purpose DSPs have meaningful share of B2B-relevant open web buying — The Trade Desk and Google’s DV360, with Amazon DSP growing fast in retail-adjacent buying and a long tail of specialist platforms operating in pockets. Everybody else lost. I was one of them with my first adtech business, PowerLinks, which didn’t make it in the world of native bidding.
The reason they lost is not ideological, and it is not operational. It is arithmetic.
The reason the orthodoxy held: hundreds of billions of auctions a day
A bid request is a network event. An SSP serialises a JSON payload describing an impression opportunity, sends it across the public internet to one or more DSPs, waits for a response inside a strict timeout window — typically 100 to 200 milliseconds on the DSP side, depending on the integration — then resolves the auction. At the open web’s current scale, the total volume of unique impression auctions runs into the hundreds of billions per day, and nets out at around 700b auctions when we make the best possible efforts to remove the hugely duplicative nature of oRTB. RTB bid request volume, counted across the duplication created by header bidding, runs into the trillions. The same impression, on the same page, at the same moment, exposed simultaneously through fifty-plus supply paths to the same buyer pool.
Each loop costs money. Compute on the DSP side to deserialise the request, run model inference, decide whether to bid and at what price, serialise the response. Egress bandwidth, often the dominant line item, billed by the hyperscalers at a premium. Storage and retrieval for the contextual signals, user identifiers, audience segments and frequency caps the bidder needs. At hundreds of millions of requests a day per DSP, the marginal cost of merely seeing the bid stream — before any working media is spent — stacks up to seven or eight figures a month. When we set out to build FunnelFuel, a B2B programmatic managed service, we decided this money would be much better invested in upgrading the best of the incumbent stack, and to borrow a phrase I over-use, we did not want to rebuild the wheel. This tech is commodity, and the cloud computing cost of listening to B2B volumes would be hugely wasteful in every sense possible, whilst adding no value. This is why the DSP 2.0 won’t live at the end of a full unthrottled bidstream, and why containerising it is so important moving forward.
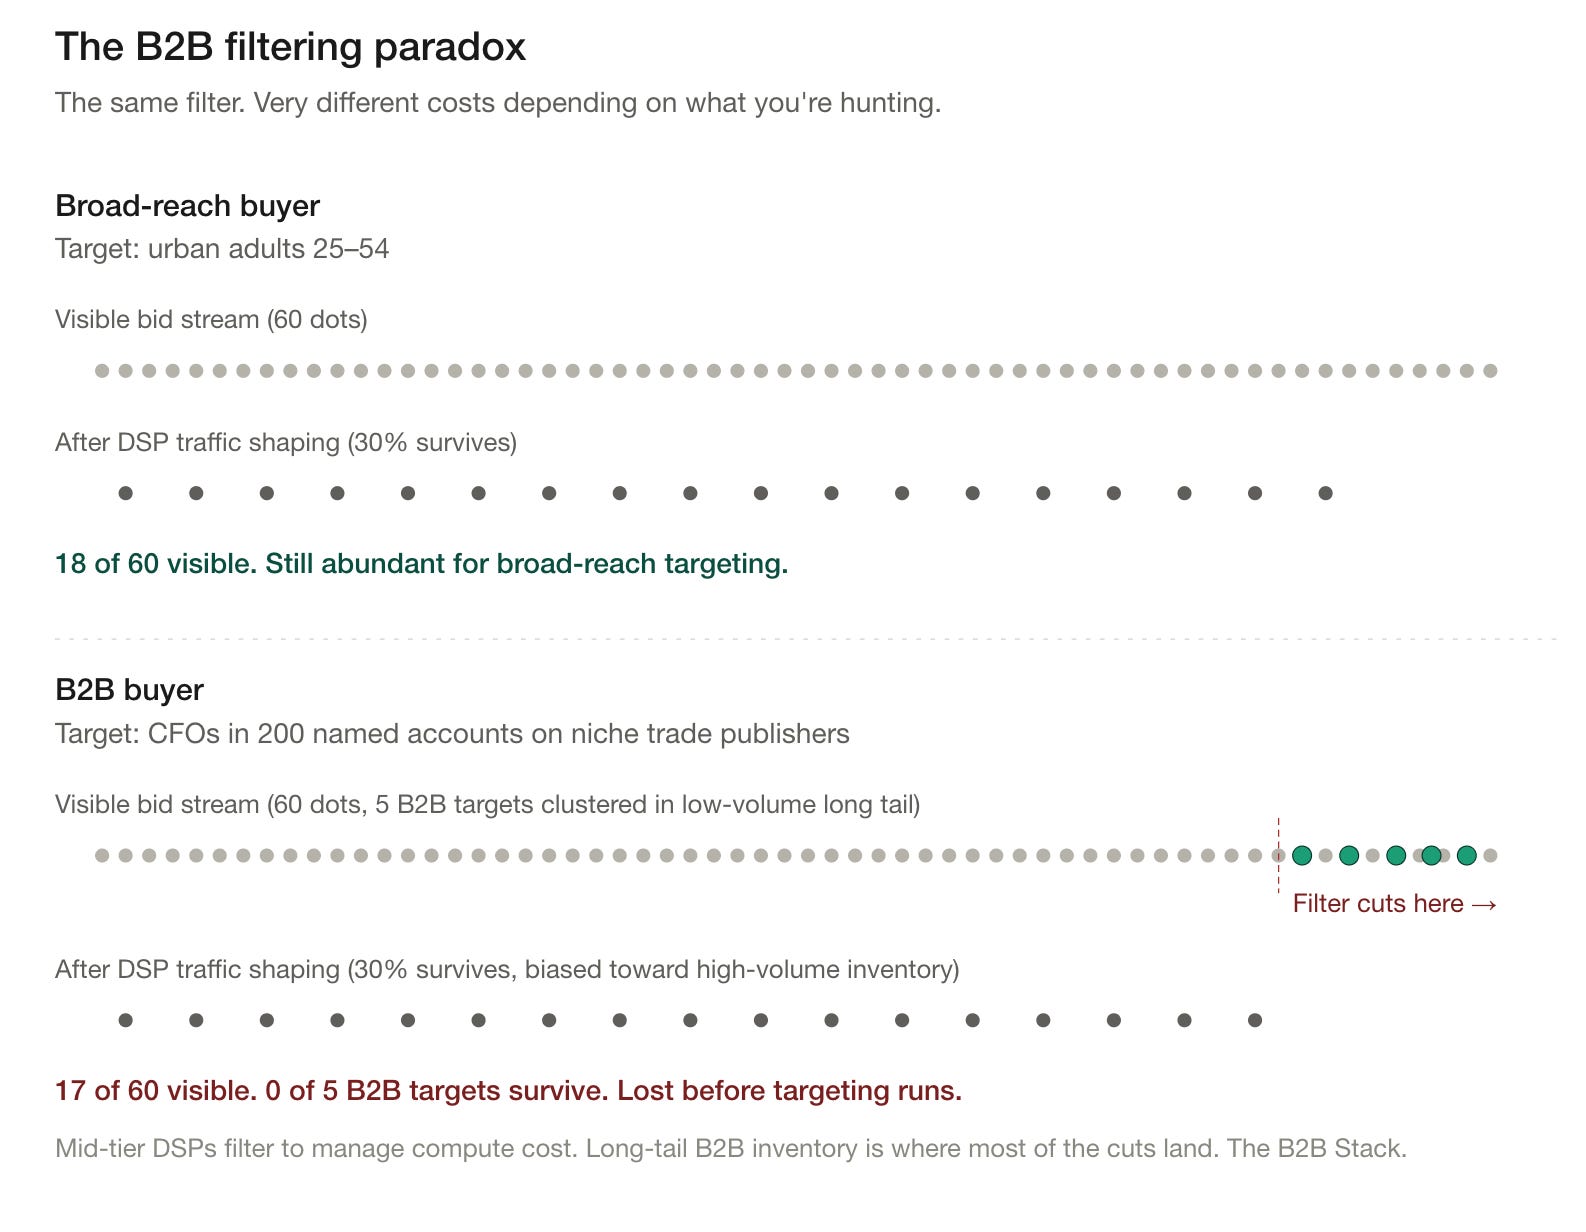
As header bidding exploded, the DSP responded rationally by filtering. Accept the share of inbound traffic that traffic shaping logic predicts is most likely to convert into winning bids, ignore the rest. Industry analyses routinely place the surviving share at somewhere between 20 and 30 per cent of available impressions.
If you are in niche audiences, like B2B, read that last line again. That is huge. Put another way - 70-80% of all B2B audiences are getting lost to bid throttling, indiscreetly, and forcing many programmatic teams to chase the scale into consumer environments, like broad content sites and gaming. This is the whole containerised audience thesis in one line - would you like to see ALL of your audience or 20-30% of it?
That QPS filter isn’t science, acknowledged by Andrew Casale on the FPC podcast linked above. It’s a heuristic for survival, calibrated on volumetric assumptions about which auctions are most likely to clear. It is, in plain language, an educated guess about which inventory matters, made at scale, with the cost of being wrong borne by the advertiser rather than the platform. In B2C, its tolerable, in B2B is is not.
For broad-reach advertisers — the people targeting urban adults 25 to 54, or seasonal car buyers, or recently engaged mortgage shoppers — this guesswork is mostly invisible. The filtered-out 70 per cent contained some signal, but the surviving 30 per cent still represents hundreds of millions of impressions, more than enough to deliver the campaign. The cost of filtering doesn’t show up in performance reports because the targets are so abundant.
For B2B, the cost is structural. We’re not buying urban adults. We’re hunting Chief Financial Officers and Chief Product Officers and IT decision-makers in specific named accounts in specific regions, often in pursuit of pipeline progression rather than top-of-funnel reach. A target account list might be two hundred companies. The buying committee inside each is six to twelve people. That’s a universe of maybe two to three thousand individuals you actually want to reach in any given quarter. Every impression discarded by upstream traffic shaping is potentially one of yours. The approach of trying to fix this by building a bidder is laughable today, but equally the opportunity to find these people in the worlds best supply pools is not.
I actually think the problem is even worse for B2B DSP buyers then the headline filtering implies, because the shaping is biased against B2B inventory before any of your targeting logic runs. Niche trade publications, technical content, finance and engineering media, vertical newsletters — the long-tail open web where B2B audiences actually spend time — are exactly the publishers whose auction volume is lowest, whose CPMs are highest, and whose impression patterns look “unprofitable” to a model optimised for broad-reach efficiency. Coca Cola and McDonalds do not want to pay the premium to reach crn.com, and they outspend Dell who will pay it. The DSP filters them out for reasons that have nothing to do with your campaign and everything to do with its own cost structure, and the democratic process of finding the best inventory for the most buyers.
Casale, on the FPC episode and earlier at the IAB Annual Leadership Meeting in February, called this dynamic an “invisible cloud tax on adtech.” That’s polite framing. A more accurate description is that the cost of looking at the open web became the dominant constraint on who could compete, and that constraint silently mortgaged the open programmatic ecosystem to the hyperscalers. Every dollar of media planning energy spent worrying about supply-path optimisation in the last five years was downstream of a structural problem that nobody could solve at the DSP layer because the cost lived at the infrastructure layer.
Below is how a containerised setup actually works day to day, and what I’d ask any DSP or curator about it before signing.